Oil Contango and Backwardation Explained
What the oil futures curve says about physical supply, and why it matters even if you only trade a CFD.
 Rayner6 min read13 September 2026
Contango and backwardation describe the shape of the oil futures curve, meaning whether a barrel for delivery in six months costs more or less than one for delivery next month. It sounds like futures jargon that a CFD trader can skip.
It is not, for two reasons. The shape tells you something genuine about whether physical supply is tight or abundant, which is the underlying driver of the price. And a CFD rolls between contracts every month, so you pay for the shape of the curve whether you understand it or not. This page covers both.
Contango is when later delivery months cost more than the front month, which usually signals ample supply. Backwardation is when later months cost less, which usually signals tight supply. A CFD trader never buys those contracts and still pays for the shape of the curve through the rollover.
What the two words mean
| Contango | Backwardation | |
|---|---|---|
| Later months | Cost more than the front month | Cost less than the front month |
| Usually signals | Ample supply | Tight supply |
| Buyers are | Happy to wait, and pay storage | Paying a premium for barrels now |
| Storage is | Filling | Draining |
| Common during | Oversupply or weak demand | Disruption or strong demand |

The logic behind contango is simple. Holding a barrel costs money in storage and financing, so if nobody urgently needs it today, the price for later delivery has to cover that cost.
Why backwardation happens at all
If storage costs money, later delivery should always be more expensive. Backwardation looks like it breaks that rule, and it does not.
When supply is genuinely tight, having the barrel in your hands right now has a value of its own. A refinery that cannot run without crude will pay more for immediate delivery than for a promise in six months. That premium can exceed the cost of storage, which flips the curve.
The curve is the physical market’s own opinion, published continuously and paid for with real money. Backwardation says buyers are competing for barrels today. Contango says they are not.
Why it matters to a CFD trader
You never buy a dated contract, and you still meet the curve every month.
A CFD tracks the front month and rolls into the next one before expiry. Because the two contracts trade at different prices, the roll produces an adjustment on your account, and the direction depends on the shape of the curve.
| Curve | Long position at the roll | Short position at the roll |
|---|---|---|
| Contango | Small cost | Small credit |
| Backwardation | Small credit | Small cost |
On a day trade it is irrelevant. On a position held for weeks it is a real number alongside the daily financing, which is covered in crude oil futures explained.
Reading the curve for a trade
This is where it becomes useful rather than academic.
- In backwardation, an inventory draw carries further. The physical market is already tight, so a draw confirms what the curve said and the move tends to hold.
- In contango, a draw fades faster. There is plenty of oil around, so one week of drawdown changes less.
- A shift from contango to backwardation is a signal in itself. It means the physical picture has genuinely changed, and it usually precedes a sustained move.
The weekly release that interacts with all of this is in how to trade the EIA inventory report.
The famous exception
Contango can become extreme. When storage is close to full and nobody can physically take delivery, the front month has almost no buyers while later months still do.
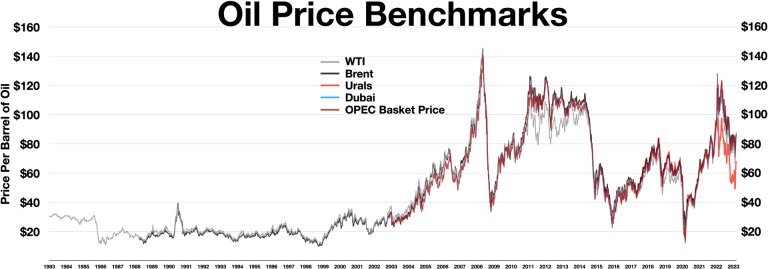
In April 2020 that situation pushed the expiring WTI contract below zero for a short period. Holders faced delivery they could not store, and paid to be relieved of it. It was a futures mechanics event rather than a statement about oil being worthless, and it is the clearest illustration of what an extreme curve means.
Retail CFD brokers handled that day very differently from one another. It is the strongest argument for not holding a leveraged oil position through an expiry you have not checked, and for reading your broker’s contract specification once.
How to actually use it
- 01As a supply readBackwardation means tight, contango means ample. That is genuine information, published by people spending real money.
- 02As a holding cost checkIf you swing trade oil, know which way the roll runs before you hold across one.
- 03As confirmationA bullish oil setup in backwardation has the physical market agreeing with it. Mild support, not a reason on its own.
What it is not is a trade on its own. There is no level and no invalidation price in a curve shape, so there is nowhere to put a stop, which is the same objection as any idea without one. The broader drivers are in what moves the crude oil price.
Keep reading
- Crude oil futures explained contract months and the rollover
- Crude oil CFDs vs futures vs ETFs why the curve decides ETF tracking
- How to trade the EIA inventory report reading a draw against the curve
- What moves the crude oil price the supply balance the curve reflects
Frequently Asked Questions
What is contango in oil?
When later delivery months cost more than the front month. It usually means supply is ample, because holding a barrel costs storage and financing and nobody urgently needs it today.
What is backwardation?
When later delivery months cost less than the front month. It usually means supply is tight, because buyers are paying a premium to have barrels now rather than a promise later.
Does contango affect a CFD trader?
Yes, through the monthly roll. A CFD tracks the front month and switches contracts before expiry, and because the two price differently the roll produces a small cost or credit depending on the curve.
Which is better for a long oil position?
Backwardation, because the roll runs in your favour and the physical market is telling you supply is tight. Contango means a small cost at each roll and a looser supply picture.
How do I know if oil is in contango?
Compare the price of the next few delivery months on any futures quote page. Rising prices further out is contango, falling prices further out is backwardation.
Why did oil go negative in 2020?
Extreme contango combined with full storage. Holders of the expiring contract faced physical delivery they could not store, so they paid to be relieved of it. It was a futures mechanics event rather than a verdict on oil.
Should I trade based on the curve shape?
Not on its own, because a curve gives no level and no invalidation price. Use it as a supply read and as mild confirmation for a setup you already have on the chart.